
RismadarVoice Reporters
September 18, 2026
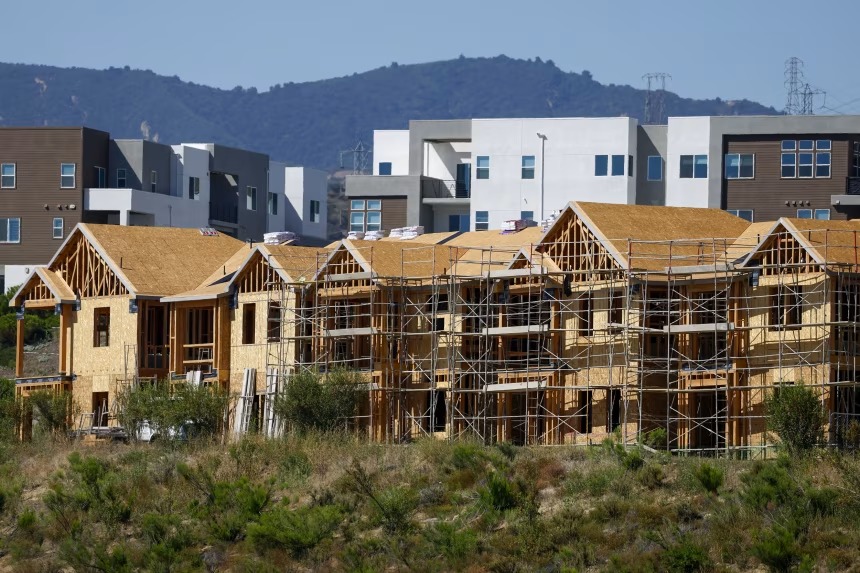
A toxic combination of surging interest rates and near-record property prices is pushing homeownership out of reach for millions of prospective buyers, compounding financial strain across the U.S. housing market.
The average 30-year fixed mortgage rate reached 7.2% this week, its highest level in 18 months, according to industry data. The sharp increase follows a brief period of relief early this year when rates dipped to 5.99% in late February.
Borrowing costs have since escalated rapidly, driven by rising 10-year Treasury yields tied to broader inflationary pressures and soaring global energy prices.
Adding to buyer headwinds, the Federal Reserve raised its benchmark interest rate this week and signalled potential further hikes to combat persistent inflation, likely keeping consumer borrowing costs elevated. Meanwhile, the national average home price stood at $429,100 in August, hovering near all-time highs.
The sharp decline in affordability is reshaping homebuying dynamics and demographics:
Pending home sales dropped 4.7% year-over-year as higher borrowing costs force buyers to delay transactions or adjust their expectations.
The median age of a first-time homebuyer has climbed to an all-time high of 40, according to the National Association of Realtors.
High housing and rental costs pushed a record 25.2 million adults under the age of 35 to live with their parents last year.
Despite the market squeeze, inventory offers a minor silver lining. Unsold home inventory rose to 1.62 million units in August, a 4.9-month supply, marking the highest stock level in over a decade and granting active buyers increased leverage during price negotiations.
Real estate professionals note that inflation across essentials like fuel and groceries, paired with high monthly mortgage commitments, is convincing many prospective buyers to remain on the sidelines until market volatility subsides.